

- OVERVIEW
The Pandora’s Box of Heatwaves and the Shipping Market
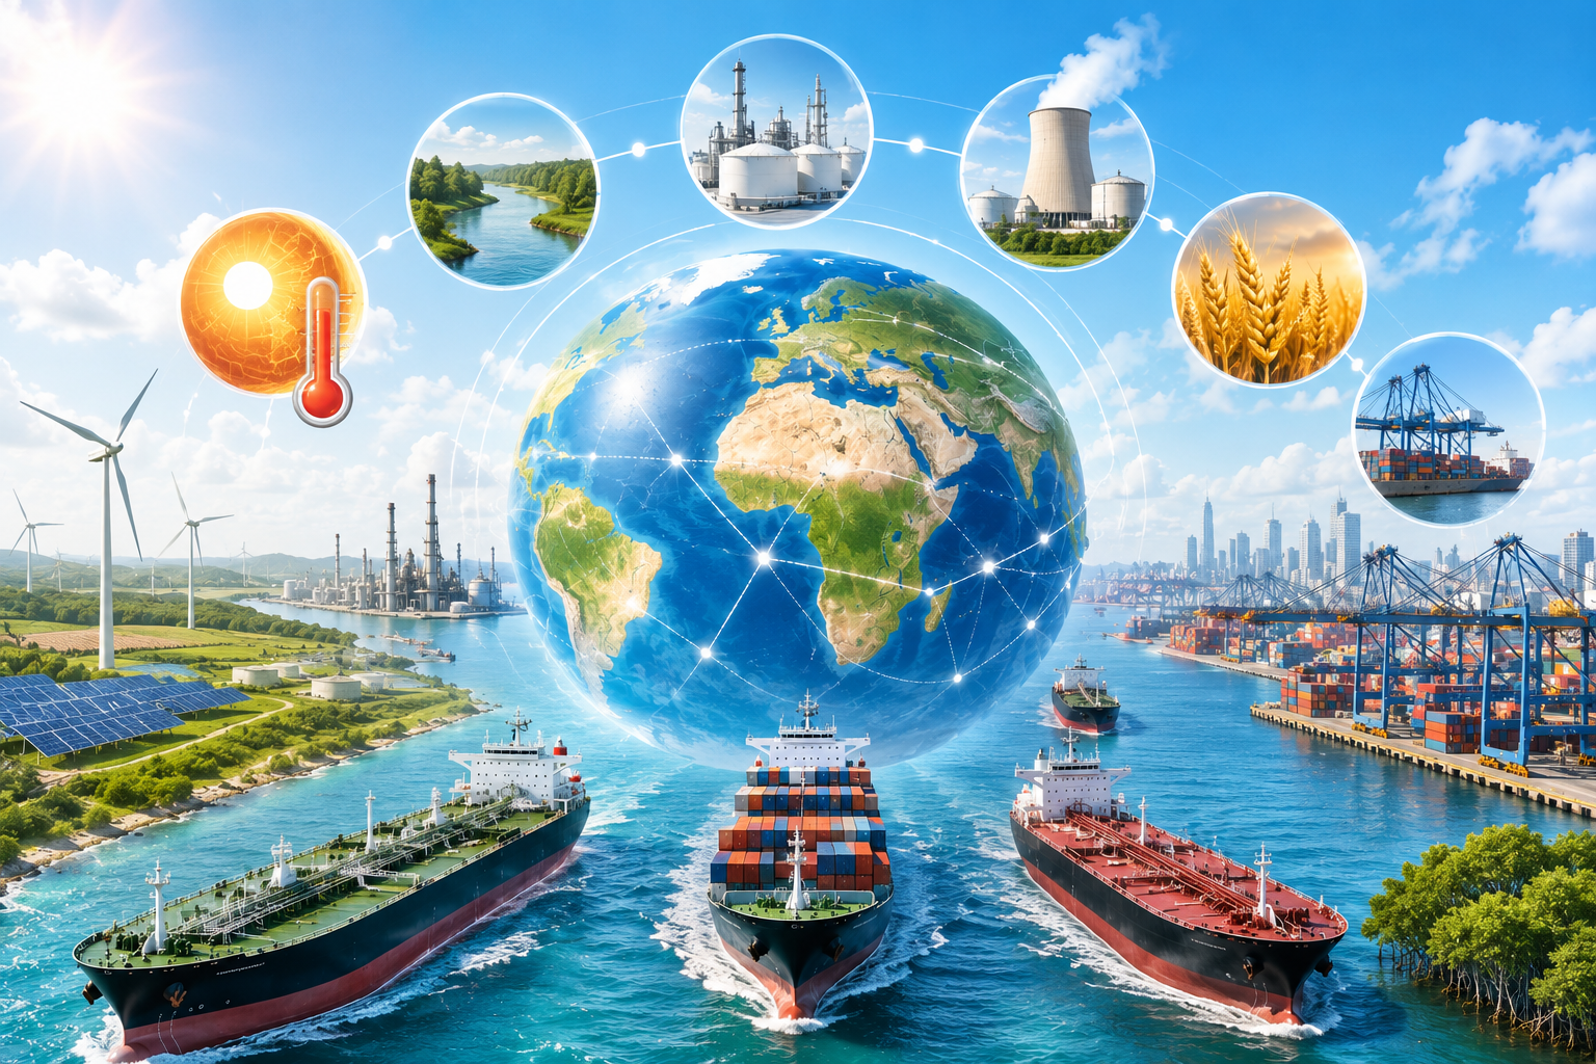
Heatwaves are often viewed as a humanitarian or environmental issue. However, for the shipping industry, prolonged periods of extreme heat may quietly open a Pandora’s Box of operational, commercial and financial challenges.
More Than Just Hot Weather
When discussing shipping risks, the industry often focuses on wars, sanctions, piracy, interest rates or oil prices. Yet heatwaves deserve equal attention because they affect almost every part of the maritime supply chain.
Extreme temperatures can influence:
- Water levels in major rivers
- Power generation and fuel demand
- Agricultural exports
- Refinery operations
- Port productivity
- Vessel operating efficiency
- Crew welfare and safety
- Cargo deterioration during voyage due to heat

El Niño and La Niña Can Reshape Shipping Conditions
Heatwaves and droughts are not isolated events. UN Trade and Development reported that severe drought in 2023 and early 2024, linked in part to El Niño, reduced Panama Canal water levels and forced vessels onto longer and more expensive routes. For completed journeys from the Americas to Asia, sailing distances increased by about 31%, while cargo volumes fell. The episode illustrates how a climate event can quickly become a freight-market event.
La Niña, by contrast, generally cools the central and eastern tropical Pacific and can shift rainfall in the opposite direction. Depending on the region, this may bring heavier rainfall, flooding and changes in tropical cyclone patterns. For shipping, the risks can move from “too little water” to “too much water”: flooded ports and hinterland networks, weather-related berth closures, stronger river currents, cargo delays and disrupted agricultural production.
Importantly, neither El Niño nor La Niña has one uniform global effect. Their shipping impact depends on geography, season and the strength of the event. Shipping should therefore treat ENSO forecasts as an early-warning indicator rather than a stand-alone freight signal.

New York bulker owner Genco Shipping & Trading this week after the company presented a slide on the potential impact of an El Nino weather pattern on water levels.
The presentation noted expert forecasts of an 81% chance of a strong El Nino event from October to December, and a 97% chance that it persists through early spring.
The El Nino pattern would make some regions wetter and others drier. It notably reduced water levels in the canal in 2023, causing a major reduction in transits and boosting hire rates for some operating sectors.
Rivers Become Less Navigable
For inland waterways such as the Rhine River in Europe, Mississippi River in the United States, Yangtze River in China and parts of South America, lower water levels mean vessels cannot safely sail fully loaded.
The consequences include:
- Reduced cargo per voyage
- More voyages required to transport the same cargo volume
- Higher inland transportation costs
- Delays in cargo reaching export terminals
When inland logistics slow, seaborne shipping schedules may also be affected.
Energy Demand Surges
During severe heatwaves, electricity consumption often rises sharply as households and industries increase air-conditioning usage.
Power utilities respond by increasing fuel consumption, including:
- LNG
- Fuel oil
- Coal
- Diesel
- Natural gas
For tanker and gas shipping markets, this may generate additional cargo movements, particularly where countries rely on imported energy.
Refineries Face Operational Stress
Extreme temperatures may reduce refinery efficiency.
High ambient temperatures can:
- Lower cooling efficiency
- Increase maintenance requirements
- Reduce operational flexibility
Unexpected refinery outages may alter regional product balances, leading to:
- Increased imports
- Emergency cargoes
- Longer trading routes
These changes may create additional opportunities for clean petroleum product tankers.
Agricultural Trade Patterns Shift
Heatwaves can reduce crop yields through drought and water shortages.
When domestic agricultural production falls, countries may increase imports of:
- Vegetable oils
- Grains
- Feedstocks
- Biofuel feedstocks
Conversely, exporting nations suffering poor harvests may reduce exports altogether.
These shifts affect demand for both tanker and dry bulk segments, particularly where edible oils and biofuel feedstocks such as palm oil, PFAD and used cooking oil are involved.
Higher Vessel Operating Costs
Heat also affects vessels directly.
Higher temperatures may result in:
- Greater air-conditioning load onboard
- Increased auxiliary engine usage
- Higher fuel consumption
- Faster deterioration of equipment exposed to extreme temperatures
Although these cost increases are relatively modest per voyage, they become meaningful over large fleets operating continuously.
Port Productivity Can Decline
Many ports around the world increasingly implement worker safety measures during extreme heat.
This may include:
- Reduced outdoor working hours
- Additional rest periods
- Temporary work stoppages
Cargo operations may therefore proceed more slowly, particularly where manual labour remains significant.
Longer port stays effectively reduce available vessel supply, which can contribute to firmer freight markets if delays become widespread.
Crew Welfare Becomes Increasingly Important
Perhaps the least discussed consequence is human performance.
Crew members working on deck under temperatures exceeding 40°C face:
- Heat exhaustion
- Fatigue
- Reduced concentration
- Increased accident risk
Protecting seafarer welfare is not merely a humanitarian responsibility—it also contributes directly to operational reliability and safety.
Cargo Deterioration During Voyage due to Heat
Possible consequences include:
- Changes in cargo viscosity or physical characteristics
- Accelerated oxidation or chemical degradation
- Increased vapour generation and pressure management requirements
- Greater risk of off-specification cargo upon arrival
- Additional cooling, ventilation or temperature-monitoring requirements
- Increased potential for quality disputes and cargo claims
Looking Ahead
Heatwaves should therefore be viewed not simply as weather events, but as another strategic market indicator.El Niño and La Niña can amplify or redistribute drought, rainfall, heat and storm risks, with consequences for waterways, ports, cargo flows, energy demand and vessel availability. A drought at a strategic canal, flooding at an export hub or a weather-driven change in commodity production can alter voyage distances, effective tonnage supply and freight rates well before the impact is visible in headline trade data.
- PLATTS TREND
| WORLD SCALE | 4-Aug-26 | 5-Aug-26 | 6-Aug-26 | 7-DAYS AVERAGE |
1-DAY CHANGE |
7-DAYS CHANGE |
7-DAYS- CHANGE |
|---|---|---|---|---|---|---|---|
| SPORE/JPN (30 KT) | 210 | 210 | 205 | 210.75 | -5 | -10 | -4.65% |
| SPORE/OZ (35 KT) | 263.5 | 263.5 | 257.5 | 265.25 | -6 | -12.5 | -4.63% |
| KOREA /OZ (35 KT) | 282.5 | 286.5 | 275 | 288.56 | -11.5 | -24 | -8.03% |
| INDIA/JAPAN (35 KT) | 220 | 220 | 215 | 211.56 | -5 | 15 | 7.50% |
| $1 = $1K | 4-Aug-26 | 5-Aug-26 | 6-Aug-26 | ||||
|---|---|---|---|---|---|---|---|
| SPORE/HK | 540 | 540 | 530 | 545.00 | -10 | -30 | -5.36% |
| KOREA/SPORE | 825 | 835 | 800 | 837.50 | -35 | -80 | -9.09% |
| KOREA/JAPAN | 585 | 585 | 575 | 591.88 | -10 | -45 | -7.26% |
| KOREA/H.K. | 735 | 735 | 720 | 740.63 | -15 | -45 | -5.88% |
| KOREA/USWC | 2,190 | 2,200 | 2,150 | 2,206.25 | -50 | -115 | -5.08% |
| WORLD SCALE | 4-Aug-26 | 5-Aug-26 | 6-Aug-26 | ||||
|---|---|---|---|---|---|---|---|
| AG/JAPAN (55 KT) | 300 | 300 | 300 | 302.50 | 0 | 0 | 0.00% |
| AG/JAPAN (75 KT) | 345 | 345 | 345 | 347.50 | 0 | 0 | 0.00% |
| OMAN G/JAPAN (55 KT) | 190 | 190 | 195 | 192.50 | 5 | 0 | 0.00% |
| OMAN G/JAPAN (75 KT) | 185 | 190 | 190 | 187.50 | 0 | 5 | 2.70% |


- SMALL TANKERS MARKET UPDATE
The regional market remains mixed, with Southeast Asia subdued while the Far East continues to tighten. Intra-SEA and Northbound activity remain soft as ample tonnage and limited chemical demand keep freight under pressure, with some owners repositioning north for better opportunities. In contrast, Intra-FEAST is firmer as August demand, limited vessel availability and potential Typhoon Dolphin disruptions tighten the market and support modest freight increases. Southbound remains one of the healthier trades, with steady chemical demand extending into September and smaller tonnage becoming increasingly difficult to secure. Westbound activity into India remains steady but fragmented, while AG trade continues to be restricted by the Strait of Hormuz situation. Overall, Far East freight shows some upside potential, while Southeast Asia remains largely flat to soft.
- REPORTED FIXTURES
| VESSEL | SIZE | GRADE | L/C | LOAD | DISCHARGE | FREIGHT | CHTRS |
|---|---|---|---|---|---|---|---|
| VNR | 9.5 | ALKYLATE | 25 – 30 AUG | MAILIAO | STRAITS | $370K L/S | CNR |
| VNR | 10 | TOL | 24 – 28 AUG | DONGGUAN | SINGAPORE | $375K L/S | CNR |
| VNR | 18 | CHEMS | 15 – 30 AUG | MID CHINA | WCI | MID $80S BSS 2/2 | CNR |
| NCC QAMAR | 35 | NAP | 16 AUG | STS SUEZ | JAPAN | WS 275 | ATS |
| LEFLAIVE | 35 | UNL | 18 AUG | SPORE | OZ | WS 257.5 | VITOL |
| NORD VICTOR | 35 | ULSD | 21 AUG | KOREA | OZ | WS 275 | ST |
- GLOBAL BUNKER PRICE REPORT
VLSFO prices continued to soften during the week as improving crude oil supply and optimism over a possible Strait of Hormuz shipping agreement reduced market concerns. Although geopolitical risks remain, easing supply fears and weaker crude prices placed downward pressure on VLSFO across most major bunkering hubs.
MGO prices declined across most major bunkering hubs during the week as lower crude oil prices weighed on the bunker market. However, the correction was partly limited by tight diesel supply and strong refining margins, which continued to provide support to marine gasoil prices despite the overall weaker market sentiment. Fujairah, Rotterdam and Houston declined. The market remained supported by ongoing supply risks in the Middle East, but higher oil production and improved crude availability helped ease upward pressure on bunker prices. As a result, price movements became more balanced across the major bunkering hubs.
HSFO prices also weakened during the week as improving oil supply expectations reduced support for the fuel oil market. While ongoing uncertainty in the Middle East prevented a sharper decline, softer crude prices and easing supply concerns continued to weigh on HSFO prices across most major bunkering hubs.
(US$/MT)
| 4-Aug | 5-Aug | 6-Aug | 3-DAYS AVERAGE |
1-DAY CHANGE |
3-DAYS CHANGE | |
|---|---|---|---|---|---|---|
| VLSFO 0.5 | ||||||
| SINGAPORE | 844.5 | 816.5 | 812.5 | 824.5 | -4.0 | -32.0 |
| FUJAIRAH | 804.5 | 768.0 | 763.5 | 778.7 | -4.5 | -41.0 |
| ROTTERDAM | 662.0 | 646.5 | 634.5 | 647.7 | -12.0 | -27.5 |
| HOUSTON | 680.0 | 667.5 | 671.0 | 672.8 | +3.5 | -9.0 |
| GLOBAL MARKET | 806.5 | 791.5 | 789.0 | 795.7 | -2.5 | -17.5 |
| MGO | ||||||
| SINGAPORE | 1205.0 | 1107.0 | 1113.5 | 1141.8 | +6.5 | -91.5 |
| FUJAIRAH | 1322.0 | 1274.5 | 1275.5 | 1290.7 | +1.0 | -46.5 |
| ROTTERDAM | 1190.5 | 1177.0 | 1146.5 | 1171.3 | -30.5 | -44.0 |
| HOUSTON | 1150.5 | 1141.0 | 1145.5 | 1145.7 | +4.5 | -5.0 |
| GLOBAL MARKET | 1312.0 | 1272.5 | 1272.0 | 1285.5 | -0.5 | -40.0 |
| IFO 380 (HSFO) | ||||||
| SINGAPORE | 588.0 | 570.0 | 580.0 | 579.3 | +10.0 | -8.0 |
| FUJAIRAH | 599.0 | 571.5 | 578.5 | 583.0 | +7.0 | -20.5 |
| ROTTERDAM | 511.0 | 508.0 | 496.0 | 505.0 | -12.0 | -15.0 |
| HOUSTON | 461.0 | 456.5 | 461.5 | 459.7 | +5.0 | +0.5 |
| GLOBAL MARKET | 620.0 | 598.0 | 604.5 | 607.5 | +6.5 | -15.5 |
- SHIPPING STOCKS MARKET WATCH
Scorpio issued $605m worth of convertible bonds in April and May while retiring more-costly secured bank debt and a Norwegian bond. While Scorpio’s convertible ride is not free, the financing has an effective interest rate of below 1%, further reducing the owner’s overall funding costs.
Giant Canadian investor Brookfield Asset Management has assumed direct control of Torm. Ownership of a 19.86% stake worth around $600m has been transferred from Oaktree Capital Management after Brookfield took 100% control of the US asset manager this week.


- SOURCES
- Intergovernmental Panel on Climate Change (IPCC). (2023). Climate Change 2023: Synthesis Report. Retrieved August 2026, from https://www.ipcc.ch
- International Energy Agency (IEA). (2025–2026). Electricity Market Reports and Analysis of Cooling and Electricity Demand. Retrieved August 2026, from https://www.iea.org
- International Maritime Organization (IMO). (2025–2026). Climate Change, Maritime Resilience and Greenhouse Gas Reduction Initiatives. Retrieved August 2026, from https://www.imo.org
- World Meteorological Organization (WMO). (2025–2026). Global Climate, Extreme Heat and Heatwave Monitoring Reports. Retrieved August 2026, from https://wmo.int
- European Commission – Joint Research Centre (JRC). (2025–2026). Drought Monitoring, European River Conditions and Inland Waterway Impacts. Retrieved August 2026, from https://joint-research-centre.ec.europa.eu
- U.S. National Oceanic and Atmospheric Administration (NOAA). (2025–2026). Heatwave, Drought and Climate Monitoring. Retrieved August 2026, from https://www.noaa.gov
- BIMCO. (2025–2026). Shipping Market Analysis and Weather-Related Disruptions to Maritime Trade. Retrieved August 2026, from https://www.bimco.org
- Drewry. (2025–2026). Maritime Supply Chain, Port Congestion and Shipping Market Analysis. Retrieved August 2026, from https://www.drewry.co.uk
- Clarksons Research. (2025–2026). Shipping Intelligence, Trade Flows and Climate-Related Market Analysis. Retrieved August 2026, from https://www.clarksons.net
- United Nations Conference on Trade and Development (UNCTAD). (2025). Review of Maritime Transport 2025. Retrieved August 2026, from https://unctad.org/publication/review-maritime-transport-2025
- Tradewinds. (2026). Investor Brookfield grabs Oaktree stake in Torm as part of takeover move. Retrieved August 2026, from https://www.tradewindsnews.com/tankers/investor-brookfield-grabs-oaktree-stake-in-torm-as-part-of-takeover-move, accessed Aug 2026
- Tradewinds. (2026). How Scorpio Tankers hitched a five-year convertible ride on the cheap. Retrieved August 2026, from https://www.tradewindsnews.com/finance/how-scorpio-tankers-hitched-a-five-year-convertible-ride-on-the-cheap
- Cru Group. (2026). How El Nino will affect the Steel Supply Chain. Retrieved August 2026, from https://www.crugroup.com/en/communities/thought-leadership/2023/how-el-nino-will-affect-the-steel-supply-chain
- Tradewinds. (2026). Return of El Nino could provide tailwinds for Genco and dry bulk trade. Retrieved August 2026, from https://www.tradewindsnews.com/bulkers/return-of-el-nino-could-provide-tailwinds-for-genco-and-dry-bulk-trade/2-1-2026566
- Maritime Hub. (2026). Panama Canal Draft Restrictions: New El Niño Measures 2026. Retrieved August 2026, from https://maritime-hub.com/panama-canal-draft-restrictions-new-el-nino-measures-2026/
- S&P Global Commodity Insights (Platts). Clean tanker freight assessments and tanker market intelligence, accessed UG 2026.
- Firstlink Research Team. (2026). Internal Market Analysis on Heatwaves, Energy Demand and Implications for the Shipping Market. Firstlink Global Pte. Ltd., Singapore.

7 Comments
It is a ‘Super El Nino’ this year, worst in at least 76 years. The impact will be severely costly for commodities and supply chain. The trick is how to batten down and find opportunities. New trade routes, substitute commodities and suppliers will emerge.
Just realized that weather is becoming an increasingly important factor for shipping. What starts as a heatwave or drought on land can quickly translate into lower water levels, port delays, shifting cargo flows and ultimately higher freight costs..
A good reminder of how closely weather, shipping, and global trade are connected.
Global warming will result in icecaps melts and it is possible to turn this calamity into an opportunity where excess liquids can be transferred to areas of excess droughs/lack of water resources due to heat. Maybe even h2o carriers with water being a scarce resource in the future.
Interesting! This is slowly becoming my weekly dose of knowledge haha.
A good reminder that weather can have a big impact on the shipping market.
Drought, heatwaves and changing weather can affect cargo flows, vessel availability and freight rates.
We should not only look at the risks, but also at the new opportunities that may come with them.
In an era of climate uncertainty, understanding weather patterns may prove as valuable as tracking freight markets.